Utah USDA Loans
Buy a home in an eligible Utah community with $0 down if you qualify.
USDA loans can make homeownership more affordable for eligible Utah buyers purchasing in qualifying rural and suburban communities.
Standard 1–4 Person Income Limit
Highest Listed 5–8 Person Limit Below
Financing Available for Eligible Buyers
Qualifying for a USDA Loan in Utah
Looking for a home in Utah? A USDA Guaranteed home loan may offer an affordable path to homeownership with 100% financing and no required down payment for eligible buyers and properties.
For 2026, the standard Utah USDA household income limit is $124,350 for a household of 1–4 people and $164,150 for a household of 5–8 people, already above the national standard. The Logan and St. George metro areas use these same figures.
Depending on the property's location, income limits can reach $149,800 for a 1–4 person household and $197,750 for a 5–8 person household in Summit and Wasatch counties.
USDA financing is not limited to isolated farmland. Many smaller cities, towns and growing communities outside Utah's densely developed Wasatch Front may contain USDA-eligible properties.
Because both household income and the exact property address matter, it is worth checking your eligibility even if you are unsure whether a home or community qualifies.
Utah USDA Eligibility Map
The map below provides an overview of Utah areas that may qualify for USDA financing. Property eligibility is determined by the exact address, so the current USDA eligibility system should always be used for final confirmation.
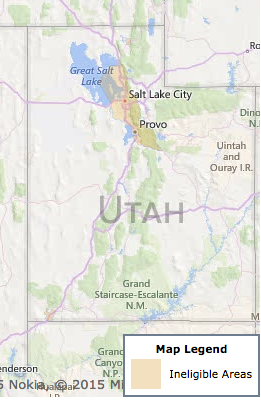 Check a Utah property address
USDA Loans Aren't Just for Farmland
Utah has many smaller cities and towns where buyers may find USDA-eligible properties. Homes outside the most densely developed portions of Salt Lake City, Provo, Ogden and St. George are often worth checking.
How the Utah USDA Loan Process Works
A straightforward path toward purchasing an eligible Utah home with no down payment.
Check Your Eligibility
Complete a quick request so we can review whether USDA financing may fit your homebuying situation.
Review Household Income
We compare your household income and household size with the correct USDA income limit for the Utah property area.
Confirm the Property Area
The exact property address is checked against the current USDA property eligibility system.
Review Your Loan Options
A Utah USDA loan specialist can explain your estimated payment, qualification requirements and next steps.
Start My ReviewPopular Utah USDA Loan Areas
USDA eligibility is determined by the exact property address. These are some of the Utah regions commonly reviewed by buyers searching beyond densely developed urban areas.
Utah USDA Income Limits
Utah's standard USDA income limit runs above the national figure, and the Wasatch Front metro areas and several counties carry increased limits on top of it.
| Utah Area | 1–4 Person Household | 5–8 Person Household |
|---|---|---|
| Standard Utah Limit — Most Rural Counties, plus the Logan UT-ID and St. George MSAs | $124,350 | $164,150 |
| Summit County, UT | $149,800 | $197,750 |
| Wasatch County, UT | $149,800 | $197,750 |
| Salt Lake City, UT HUD Metro FMR Area | $141,100 | $186,300 |
| Ogden, UT MSA | $138,600 | $183,000 |
| Provo-Orem-Lehi, UT MSA | $136,500 | $180,200 |
| Tooele County, UT HUD Metro FMR Area | $126,850 | $167,450 |
Limits shown are FY 2026 USDA Guaranteed Housing Program moderate-income limits.
Which Utah Income Limit Applies?
The correct USDA income limit depends primarily on the property's location and the number of people who will occupy the home.
Property Location
The county or metropolitan area where the Utah home is located determines which USDA income limit applies. Not every named metro area is higher than the standard, so the correct figure should be confirmed for the specific address.
Household Size
USDA lists one Guaranteed Loan limit for households of 1–4 people and a higher limit for households of 5–8 people.
Total Household Income
Income from adult occupants may need to be counted for USDA eligibility even when that household member is not applying for the mortgage.
Utah USDA Loan Features
Affordable mortgage benefits designed to help eligible Utah homebuyers.
No Down Payment
Eligible buyers may finance 100% of the home's purchase price without making a traditional down payment.
Fixed Interest Rate
USDA Guaranteed loans use 30-year fixed-rate financing, helping keep principal and interest payments predictable.
Utah Communities
USDA loans are available in qualifying rural and suburban communities throughout Utah.
Flexible Credit Guidelines
USDA guidelines may provide flexible qualification options for borrowers who meet applicable program and lender requirements.
New or Existing Homes
USDA financing may be used for qualifying new construction or an eligible existing primary residence.
Ready to Get Started?
Complete a quick request and receive a personalized Utah USDA loan eligibility review.
Start NowCheck Your Utah USDA Eligibility
USDA loans are available in eligible rural and suburban areas throughout Utah. We can quickly:
- Review total household income eligibility
- Identify the correct limit for your Utah county or metro area
- Confirm whether the property location may be USDA eligible
- Provide a preliminary payment estimate
- Explain qualification requirements and next steps
Utah USDA Loan Questions
Helpful answers about Utah USDA property eligibility, income limits and financing.
Can I buy a home in Utah with no down payment?
Yes. Eligible homebuyers may be able to finance 100% of the purchase price through a USDA Guaranteed loan. That means no down payment is required when USDA and lender qualification requirements are satisfied.
What areas of Utah are eligible for USDA loans?
USDA loans are available in qualifying rural and suburban communities throughout Utah. Eligibility is determined by the exact property address, so each home should be checked against the current USDA property eligibility system.
What is the 2026 USDA income limit in Utah?
The standard FY 2026 Utah USDA Guaranteed Loan income limit is $124,350 for households of 1–4 people and $164,150 for households of 5–8 people. The Salt Lake City, Ogden and Provo-Orem-Lehi metro areas and Summit, Wasatch and Tooele counties have higher limits.
Why are the Summit and Wasatch county limits the highest?
USDA sets limits from local income and housing data. Summit and Wasatch counties, which include the Park City and Heber areas, are listed at $149,800 for households of 1–4 people and $197,750 for households of 5–8 people, above every Utah metro area.
What is the USDA income limit around Salt Lake City?
For FY 2026, the Salt Lake City UT HUD Metro FMR Area has a USDA Guaranteed Loan moderate-income limit of $141,100 for households of 1–4 people and $186,300 for households of 5–8 people. Property eligibility is a separate test, and the developed Wasatch Front generally does not qualify.
Do the Logan and St. George areas have higher limits?
No. Both the Logan UT-ID MSA and the St. George MSA use the same figures as the standard Utah limit, $124,350 and $164,150. Being listed as a metro area does not automatically mean a higher limit applies.
Does USDA use borrower income or household income?
USDA income eligibility is based on qualifying household income. Income received by adult household occupants may need to be considered even when an adult household member is not listed as a borrower on the mortgage.
Is there a maximum USDA loan amount in Utah?
USDA Guaranteed loans do not use one fixed statewide maximum loan amount. The amount a borrower can qualify for depends on factors including income, debts, credit, interest rate, property taxes, homeowners insurance and other underwriting requirements.
Can I use a USDA loan for an existing Utah home?
Yes. USDA financing may be used for an eligible new or existing primary residence as long as the home is located in an approved area and satisfies applicable property and program requirements.
How do I start a Utah USDA loan prequalification?
Complete the quick online prequalification request. A USDA loan specialist can review your household size, household income, estimated credit profile, proposed property location, potential payment and next steps.
Income limits shown on this page are FY 2026 USDA Single Family Housing Guaranteed Loan Program moderate-income limits published by USDA Rural Development. Limits and program guidelines may change. Final eligibility depends on verified household income, household size, property location, credit qualification, debt-to-income ratios and current USDA and lender requirements. For households larger than eight people, additional USDA calculations apply.
Ready to See If You Qualify for a Utah USDA Loan?
Start your Utah USDA home loan review today. A USDA loan specialist will review your information and contact you with your available options.